For the past several years, insurance conversations across Colorado’s Front Range have been dominated by one theme: rising premiums. Homeowners from Pueblo to Fort Collins, along with business owners throughout the Front Range, have experienced substantial rate increases, tighter underwriting guidelines, higher deductibles, and fewer carrier options.
Today, however, there are encouraging signs that the market may be entering a new phase.
While Colorado remains one of the most challenging property insurance environments in the country due to hail, wildfire exposure, and increasing reconstruction costs, many insurance carriers are beginning to show renewed appetite for growth. In some cases, that’s translating into lower rates, more flexible underwriting, and increased competition for quality risks.
At Brukhouse Insurance, we’re seeing more opportunities for clients to shop coverage, improve pricing, and secure better policy terms than we’ve observed in several years.
Understanding Market Cycles
Insurance operates in cycles.
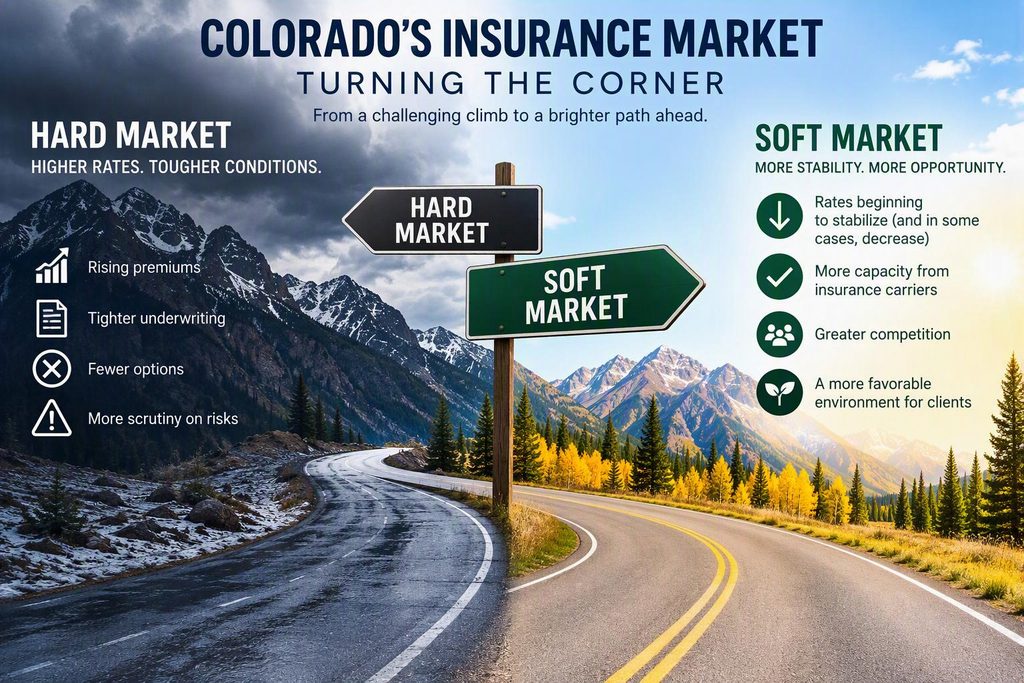
A “hard market” occurs when carriers experience poor profitability, large catastrophe losses, and rising claims costs. During hard markets, insurers typically:
- Raise premiums
- Restrict underwriting
- Reduce capacity
- Increase deductibles
- Decline higher-risk properties
Now the landscape is beginning to change.
Industry reports show improved profitability among property and casualty carriers, increased capacity, and greater competition for desirable risks. Nationally, several market surveys are reporting softening conditions, particularly for property insurance and well-performing accounts. [ciab.com], [ajg.com], [marsh.com], [digital.casact.org]
Colorado’s homeowners insurance market has been entrenched in a hard market since roughly 2020. According to state and industry data, homeowner premiums rose dramatically as carriers responded to record hail storms, destructive wildfires, inflation-driven rebuilding costs, and increasing claim severity. Colorado homeowners saw premium increases significantly above national averages during this period. [coloradosun.com], [governorso…lorado.gov]
Why the Market Is Beginning to Soften
Several factors are contributing to the shift.
Improved Carrier Results
After multiple years of aggressive rate increases, many insurers have restored profitability. Property and casualty carriers have reported stronger underwriting results and healthier combined ratios, giving them more confidence to pursue growth. [digital.casact.org]
More Competition
National market reports now indicate increasing carrier capacity and a renewed desire for premium growth. As insurers compete for business, pricing pressure naturally begins to ease. [ciab.com], [ajg.com], [marsh.com]
Better Risk Analytics
Many carriers have adopted more advanced modeling tools. Rather than declining entire ZIP codes, insurers are increasingly evaluating individual property characteristics such as roof age, construction features, mitigation efforts, and loss history. [crcgroup.com]
Increased Mitigation Efforts
Colorado homeowners have become more proactive in addressing risk. Impact-resistant roofing, defensible space around homes, water leak detection devices, and updated electrical systems can all help improve carrier appetite. State leaders have also prioritized homeowner mitigation programs aimed at reducing future losses. [governorso…lorado.gov], [cbsnews.com]
Where We’re Seeing Positive Changes on the Front Range
The softening trend does not mean every property will receive a rate reduction.
Homes located in severe wildfire corridors or those with significant claims history may still experience challenges. However, many Front Range properties are seeing improved renewal results.
Some of the most common improvements include:
- Smaller annual rate increases
- Flat renewals after years of increases
- Expanded carrier options
- Reduced restrictions on roof age
- Increased acceptance of homes with prior claims
- More flexible replacement cost parameters
- Improved bundling opportunities
Compared to recent years, that’s meaningful progress.
Carriers Expanding Their Appetite
For many homeowners, a “win” today may simply be receiving a renewal increase of 3% instead of 20%.
As independent agents, we work with multiple carriers and monitor underwriting changes closely. While carrier guidelines change frequently and vary by individual risk, several companies have demonstrated increased interest in growing market share throughout Colorado.
Safeco
Safeco, a Liberty Mutual company, has become more competitive for many Front Range homeowners and auto clients.
We’re seeing:
- More aggressive bundled pricing
- Increased willingness to quote preferred homes
- Improved competitiveness for newer roofs
- Strong package discounts when combining home and auto
For homeowners who were uncompetitive with Safeco two or three years ago, it may be worth taking another look.
Travelers
Travelers has continued refining its appetite in Colorado and has remained active in pursuing well-maintained homes with favorable loss histories.
Areas where Travelers has become increasingly attractive include:
- Newer construction homes
- Homes with impact-resistant roofing
- Multi-policy households
- Higher-value properties
Travelers has also maintained a reputation for underwriting consistency during a period when some competitors substantially limited new business.
Nationwide
Nationwide remains a strong option for many Front Range homeowners and has invested heavily in risk-selection technology and mitigation incentives.
Notable advantages include:
- Roof-age flexibility on qualifying risks
- Discounts tied to protective devices
- Competitive multi-policy pricing
- Smart-home technology incentives [nationwide.com], [nationwide.com]
Mutual and Regional Carriers
Several regional mutual companies that reduced appetite during the peak of the hard market are gradually becoming more active again.
Many of these carriers:
- Value long-term homeowners
- Offer favorable claim service reputations
- May provide underwriting flexibility that national carriers cannot
An experienced independent agency can help identify which regional markets are currently accepting new business in specific Front Range communities.
Commercial Insurance Is Improving Too
The softening trend isn’t limited to personal insurance.
Many commercial insurance buyers are beginning to benefit as well.
Recent market surveys indicate increased capacity and falling prices in several commercial property segments. Businesses with strong loss control practices are often finding additional carrier options and improved renewal negotiations. [ciab.com], [ajg.com]
Industries seeing improved competition may include:
- Professional services
- Office risks
- Contractors with strong safety programs
- Real estate investors
- Light manufacturing
- Retail operations
However, commercial auto remains challenging due to claim severity and litigation trends. Businesses with vehicle fleets should still expect underwriting scrutiny and potential rate pressure. [marsh.com]
What Still Isn’t Improving
It’s important to maintain realistic expectations.
Colorado remains one of the most catastrophe-exposed insurance markets in the country.
Several challenges continue to affect pricing:
Hail Losses
For many Front Range communities, hail remains the single largest driver of property insurance costs. State officials estimate that hail accounts for a substantial percentage of homeowner premiums across much of Colorado. [governorso…lorado.gov], [cbsnews.com]
Wildfire Exposure
Properties located in mountain-interface areas and fire-prone regions still face underwriting restrictions from many insurers. While some guidelines are loosening, wildfire remains a key concern. [doi.colorado.gov], [governorso…lorado.gov]
Reconstruction Costs
Although inflation has moderated compared to peak levels, building materials and labor remain expensive.
As a result, replacement cost estimates continue to increase, putting upward pressure on premiums.
Prior Claims
Properties with multiple water claims, hail claims, or liability losses can still encounter limited options and higher premiums.
What Homeowners Can Do Right Now
If you’re a homeowner on the Front Range, now is an excellent time to review your insurance program.
Consider taking these steps:
Shop Your Coverage
Many consumers became accustomed to accepting annual increases because every carrier was raising rates simultaneously.
That is no longer necessarily the case.
Differences between carriers can now be substantial.
Review Your Roof
Homes with newer roofs or impact-resistant roofing materials often qualify for better pricing and broader carrier options.
Bundle Policies
The gap between standalone and bundled pricing has grown significantly.
Combining home, auto, umbrella, and other policies often produces meaningful savings.
Improve Risk Characteristics
Simple improvements can make a difference:
- Leak detection devices
- Security systems
- Smart-home monitoring
- Wildfire mitigation measures
- Updated electrical or plumbing systems
Many carriers increasingly reward proactive risk management. [crcgroup.com]
The Bottom Line
The Colorado insurance market is not returning to the ultra-soft conditions of a decade ago, and homeowners should not expect dramatic premium reductions across the board.
However, after several difficult years, there are clear signs that conditions are improving.
More insurers are competing for business. Underwriting has become more flexible. Rate increases are moderating. And in some cases, homeowners and businesses are finding meaningful savings by moving to carriers that are actively seeking growth.
For Front Range residents, that is welcome news.
The key is understanding that every carrier’s appetite is different. A company that declined a home two years ago may be eager to quote it today. Likewise, a carrier that was once the cheapest option may no longer be the most competitive.
Working with an independent agency that continuously monitors carrier changes can help ensure you’re taking advantage of the opportunities created by this evolving market.
Ready for an Insurance Review?
If you’ve experienced significant premium increases over the past several years, now may be the right time to revisit your options. The team at Brukhouse Insurance can compare multiple carriers, evaluate coverage gaps, and help determine whether today’s changing market can work in your favor.
Contact Brukhouse Insurance today for a complimentary policy review and market comparison. The softening market may create opportunities that weren’t available just a year ago.

 Summer Toys, Serious Protection: Are You Properly Insured?
Leave a Reply